
⚡ Quick Answer: How to Report Consumer Fraud
- Immediate Action / Statutory Deadline: Initiate bank chargebacks under Regulation E (60-day window) or Fair Credit Billing Act (FCBA 60-day window) and preserve all transactional correspondence.
- Primary Regulatory Agency: Federal Trade Commission (FTC) via ReportFraud.ftc.gov and your State Attorney General Consumer Protection Division.
- Statutory / Legal Remedy: Restitution through state Unfair and Deceptive Acts and Practices (UDAP) statutes, statutory damages, and civil action in Small Claims Court up to statutory jurisdictional limits.
How Do I Report Consumer Fraud?
You can report consumer fraud directly to the Federal Trade Commission (FTC) and your state attorney general’s office. Provide details about the deceptive business practices, hidden fees, or undelivered goods. The FTC uses this data to identify patterns, launch federal investigations, and shut down nationwide fraudulent operations.
- Gather Evidence: Compile receipts, contracts, emails, misleading advertisements, and bank statements showing the fraudulent transactions.
- File Your Report: Submit a detailed fraud report at ReportFraud.ftc.gov and contact your state consumer protection division.
- Follow Up: Dispute the fraudulent charges with your bank or credit card provider to initiate a chargeback process.
When dishonest merchants, misleading contractors, deceptive subscription services, or predatory financial platforms cheat citizens out of hard-earned money, victims often feel powerless. Knowing how to report consumer fraud to the correct regulatory and enforcement authorities is the most critical step to halting unlawful commercial practices, recovering stolen funds, and triggering official investigations. Deceptive commerce violates federal statutes enforced by the Federal Trade Commission (FTC) and the Consumer Financial Protection Bureau (CFPB), alongside powerful state-level Unfair and Deceptive Acts and Practices (UDAP) laws.
Filing an actionable consumer complaint requires moving beyond informal customer service grievances. Regulatory investigators and civil judges require structured evidentiary documentation: signed transaction receipts, promotional printouts, contemporaneous telephone logs, and precise statutory violation citations. This master guide provides the complete legal framework, filing protocols, forensic evidence assembly checklists, and a formal pre-suit dispute letter template to hold deceptive commercial entities accountable.
Recognizing Actionable Consumer Fraud Under Federal and State Law
Consumer fraud is not merely poor customer service or dissatisfaction with a product. Under Section 5 of the Federal Trade Commission Act (15 U.S.C. § 45) and corresponding state “mini-FTC” acts, consumer fraud occurs when an entity engages in unfair methods of competition and unfair or deceptive acts or practices in commerce. A representation, omission, or practice is deceptive if it is likely to mislead a consumer acting reasonably under the circumstances to the consumer’s financial detriment.
Common Forms of Actionable Deceptive Commerce
- Negative Option Billing & Dark Patterns: Deceptive continuity programs that enroll consumers in recurring credit card subscriptions without clear and conspicuous disclosure or simple 1-click cancellation mechanisms (violating the Restore Online Shoppers’ Confidence Act, ROSCA, 15 U.S.C. § 8401).
- Bait and Switch Schemes: Advertising merchandise or services at an attractive price with no bona fide intent to sell them as advertised, steering consumers toward higher-priced alternatives.
- Deceptive Pricing and Hidden Surcharges: Failing to disclose mandatory service fees, bogus administrative add-ons, or drip pricing before transaction commitment.
- False Advertising & Omission of Material Terms: Misrepresenting vehicle history reports, product specifications, warranty coverage, or licensing status.
- Contractor & Service Provider Fraud: Demanding substantial upfront deposits, failing to pull required municipal building permits, and abandoning job sites without performing agreed structural work.
Forensic Evidence Assembly: Building an Indisputable Dossier
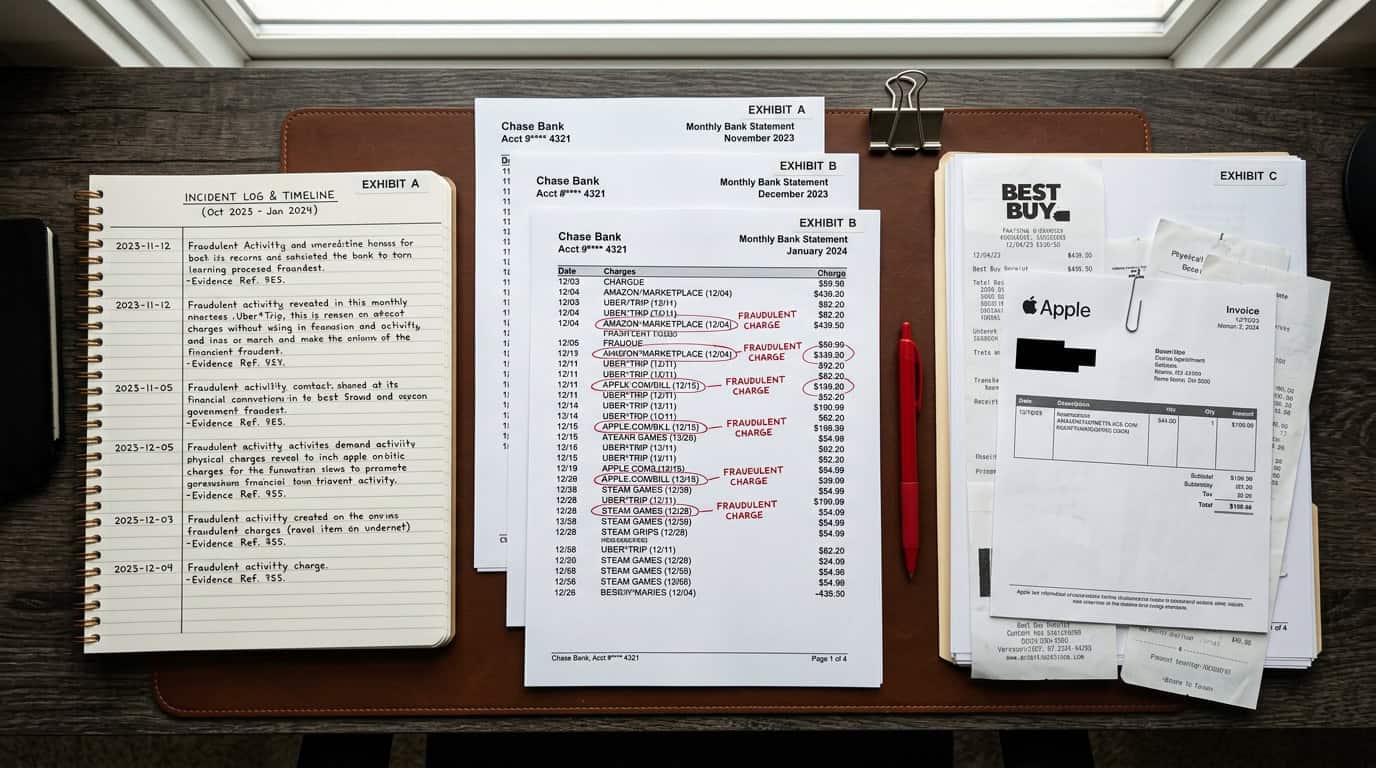
Regulatory agencies receive thousands of inquiries every month. Complaints supported by organized forensic evidence receive immediate priority triage from investigators. Before initiating portal filings, assemble an Evidentiary Dossier structured into five distinct verification categories:
- The Transactional Foundation: Complete copies of the original written agreement, retail sales contract, invoice, order confirmation email, terms of service, and signed receipt. Highlight clauses where the business explicitly made promises regarding pricing, delivery dates, or performance specifications.
- Proof of Monetary Outlay: Unredacted credit card statements, cancelled check copies front and back, ACH bank debit confirmations, or wire transfer receipts showing exact dates, amounts, and recipient merchant account numbers.
- Contemporaneous Marketing Capture: Screenshots or PDF web archives of the merchant’s advertising copy, promotional emails, social media ads, and checkout screens demonstrating deceptive claims. Ensure URLs and timestamps are visible.
- Chronological Incident Log: A date-and-time ledger documenting every telephone conversation, email exchange, physical store visit, and customer support ticket. Record employee names, representative ID numbers, and direct quotes.
- Prior Written Notice of Dispute: Copies of your formal written dispute letters sent to the merchant’s corporate headquarters, accompanied by United States Postal Service (USPS) Certified Mail tracking confirmations and signed green cards (Form 3811).
Multi-Stage Consumer Fraud Escalation Roadmap
Stage 1: Banking Lockdown
Invoke Reg E (ACH) or FCBA (Credit Card) within 60 days of statement date to dispute unauthorized or fraudulent merchant charges.
Stage 2: Federal Portals
Submit complaints to FTC ReportFraud.ftc.gov and CFPB portal to feed national law enforcement databases (Consumer Sentinel Network).
Stage 3: State AG & Licensing
File official complaints with your State Attorney General Consumer Protection Bureau and industry-specific professional licensing boards.
Stage 4: Civil Small Claims
Issue statutory 30-day pre-suit demand letter. File in Small Claims Court for actual damages plus statutory treble damages under state UDAP laws.
Step-by-Step Filing Across Federal, State, and Regulatory Agencies
Understanding the jurisdictional boundaries of consumer protection agencies prevents wasted effort and ensures your filing triggers real investigatory action.
1. Federal Trade Commission (FTC)
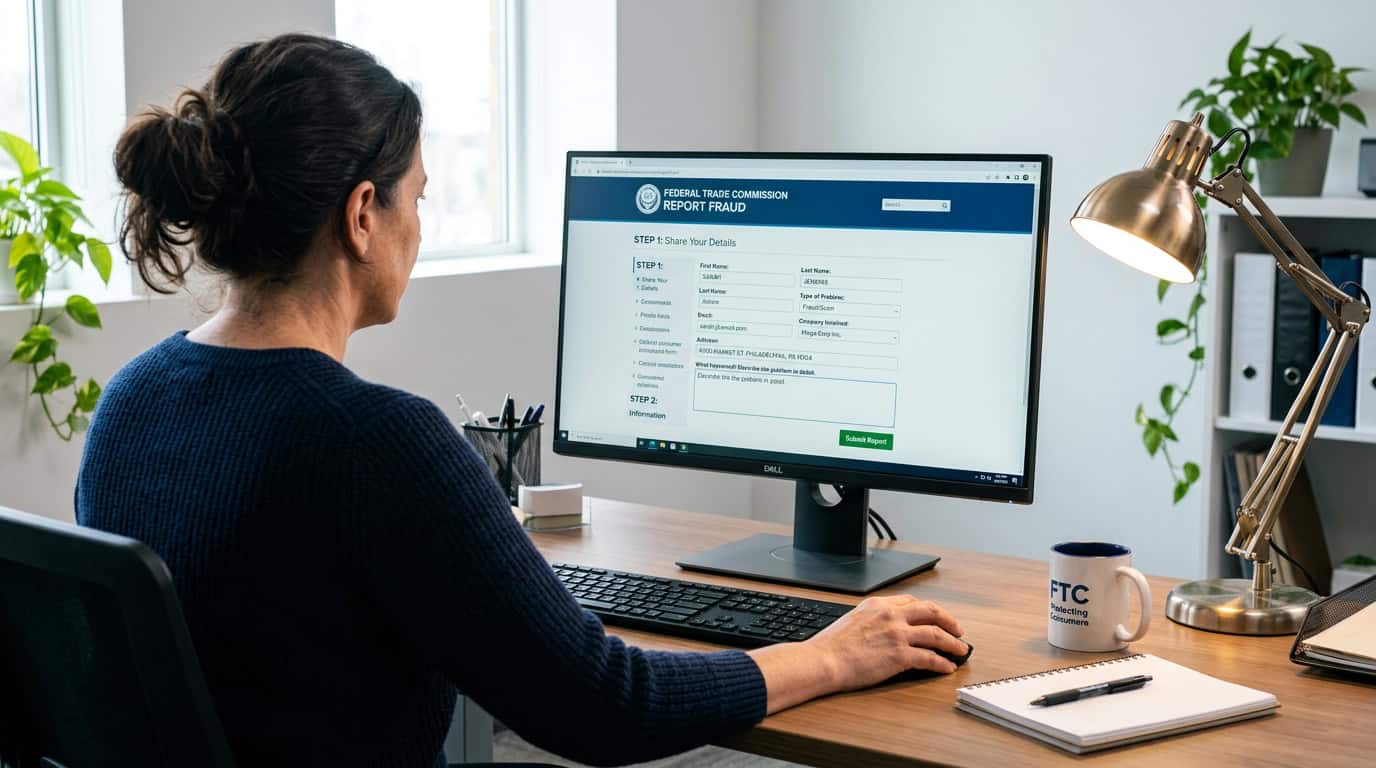
The FTC is the primary federal agency policing deceptive trade practices. While the FTC does not resolve individual billing disputes on behalf of single citizens, every report feeds directly into the Consumer Sentinel Network—a secure investigative database accessed by more than 2,800 federal, state, and local law enforcement agencies across the United States. When multiple consumers report the same entity, the FTC initiates federal injunctive enforcement actions, freezing assets and returning hundreds of millions of dollars in consumer redress.
- Filing Portal: ReportFraud.ftc.gov
- Toll-Free Hotline: 1-877-FTC-HELP (1-877-382-4357)
- Key Data Required: Merchant legal corporate name, website URL, corporate physical address, total financial loss, and specific false representations.
2. Consumer Financial Protection Bureau (CFPB)
If the deceptive practice involves a consumer financial product—including deceptive auto financing, mortgage lending, credit reporting agencies, debt collection, payday loans, or banking fees—the CFPB is the federal regulator with binding individual dispute authority. Unlike the FTC, financial institutions regulated by the CFPB are required by federal rule to provide an official written response to your complaint within 15 calendar days.
- Filing Portal: ConsumerFinance.gov/complaint
- Toll-Free Hotline: 1-855-411-2372
3. State Attorney General Consumer Protection Division
Your State Attorney General is the most potent regulatory ally for individual restitution. State AGs possess broad subpoena powers under state Unfair and Deceptive Acts and Practices (UDAP) statutes (such as California’s UCL § 17200, Texas Deceptive Trade Practices Act, or New York General Business Law § 349). Most state AG offices operate formal Consumer Mediation Units that directly contact the offending business, demand an immediate response, and mediate full restitution.
- Directory of State AGs: Consult our comprehensive directory on How to Report by State to connect directly to your local state bureau.
- Filing Strategy: Submit your complaint simultaneously to both the State AG where you reside and the State AG where the business maintains its corporate headquarters.
Statutory Pre-Suit Demand & Dispute Notice Template
Under many state deceptive trade practice statutes, sending a formal written pre-suit demand letter via certified mail is an absolute statutory prerequisite to recovering double or treble damages and attorney fees. Enclosing your dispute in this standardized format creates binding legal notice, starting statutory response countdowns.
TRACKING NO: [Insert USPS Certified Mail Tracking Number]
DATE: [Insert Date]
TO:
Legal & Compliance Department
[Merchant / Business Legal Corporate Name]
[Corporate Headquarters Address]
[City, State, ZIP Code]
FROM:
[Your Full Legal Name]
[Your Mailing Address]
[City, State, ZIP Code]
[Your Telephone Number]
[Your Email Address]
RE: STATUTORY NOTICE OF CONSUMER DISPUTE AND PRE-SUIT DEMAND UNDER STATE UNFAIR AND DECEPTIVE ACTS AND PRACTICES (UDAP) LAWS
ACCOUNT / ORDER REFERENCE: [Insert Order #, Account #, or Transaction Reference]
To Whom It May Concern:
This letter serves as formal written notice under applicable state Unfair and Deceptive Acts and Practices statutes (including but not limited to [Insert State Deceptive Trade Practices Act, e.g., Cal. Civ. Code § 1750 et seq. / Tex. Bus. & Com. Code § 17.41 et seq.]) that [Merchant Legal Name] has engaged in deceptive and unlawful commercial conduct regarding transactions conducted on or about [Insert Transaction Date].
1. FACTUAL SUMMARY OF DECEPTIVE CONDUCT:
On [Insert Date], I entered into an agreement with your business for [Insert Product or Service Description] in the total amount of $[Insert Dollar Amount]. At the time of transaction, your representatives and promotional materials represented that [Describe False Claims or Omissions, e.g., the service had no recurring fees / the vehicle had never been in an accident / the work would be fully permitted].
In truth and in fact, [Explain Actual Reality, e.g., unauthorized monthly fees of $XX were billed / the vehicle frame was severely damaged / work was abandoned without permits].
2. STATUTORY VIOLATIONS:
Your conduct constitutes unlawful, unfair, and fraudulent business acts under applicable federal and state law, including Section 5 of the FTC Act (15 U.S.C. § 45) and State UDAP provisions prohibiting false advertising, deceptive omissions of material facts, and unconscionable commercial actions.
3. DEMAND FOR COMPLETE SETTLEMENT:
To resolve this matter without formal administrative adjudication or civil litigation, I hereby demand that [Merchant Legal Name] provide a full refund in the amount of $[Insert Exact Restitution Amount] within thirty (30) calendar days from receipt of this notice.
4. RESERVATION OF RIGHTS AND ESCALATION NOTICE:
If full restitution is not received within thirty (30) days, I will immediately:
(a) File formal complaints with the Federal Trade Commission and Consumer Financial Protection Bureau;
(b) Submit a sworn complaint with the Consumer Protection Division of the Office of the Attorney General in [Your State] and [State of Corporate Headquarters];
(c) Initiate civil litigation in Small Claims Court seeking actual damages, statutory treble damages, civil penalties, and allowable court costs under state law.
Payment must be remitted by cashier’s check or certified funds mailed to my address above.
Sincerely,
__________________________________________
[Your Full Legal Name, Signed]
[Your Full Legal Name, Printed]
Enclosures: Exhibit A (Purchase Agreement / Invoice), Exhibit B (Bank / Credit Card Statement), Exhibit C (Written Marketing Representation)
Consumer Protection Myth vs. Legal Reality
Myth: “The merchant’s terms say ‘All Sales Final / No Refunds’, so I have no legal right to my money back.”
Legal Reality: Disclaimers of ‘as-is’ or ‘no refunds’ do NOT protect a business against claims of fraud, fraudulent inducement, or material misrepresentation. A contractual clause attempting to waive liability for deceptive trade practices is void as against public policy under both state UDAP statutes and federal law.
Myth: “Filing a complaint with the Better Business Bureau (BBB) forces the business to refund my money.”
Legal Reality: The BBB is a private non-profit trade organization with zero regulatory, investigatory, or enforcement authority. Businesses can ignore BBB complaints without statutory consequence. Regulatory enforcement requires filing with your State AG, the FTC, the CFPB, or municipal licensing boards.
Small Claims Court Litigation and Civil Recovery Protocols
If administrative mediation and pre-suit demands fail to secure restitution, filing an action in your municipal or county Small Claims Court provides direct judicial recovery. In Small Claims Court, you do not need an attorney to present your case. Jurisdictional financial limits range from $2,500 to $25,000 depending on your state (consult our Small Claims Court Checklists & State Limits for exact figures).
To succeed at your hearing, bring three identical sets of your Evidentiary Dossier: one for the judge, one for the opposing party, and one for your testimony notes. Present your claim clearly using the 3-Step Admissibility Framework: (1) Establish the valid commercial agreement and payment, (2) Demonstrate the merchant’s explicit false representation or unperformed obligation, and (3) Provide exact financial accounting of your unremedied damages. In many jurisdictions, demonstrating willful deceptive practices allows the judge to award double or treble damages under state consumer protection statutes.
Before You Go: Citizen Protection Protocol
Protecting yourself against unlawful practices requires swift action, methodical documentation, and strict adherence to statutory deadlines. Preserve all original agreements, maintain contemporaneous call notes, and send formal correspondence via certified mail with return receipt requested.
Frequently Asked Questions
What federal agencies hold primary enforcement jurisdiction over consumer fraud?
The Federal Trade Commission (FTC) investigates interstate commercial fraud, deceptive advertising, and telemarketing abuse under 15 U.S.C. § 45. The Consumer Financial Protection Bureau (CFPB) enforces consumer financial protection laws against banks, lenders, credit bureaus, and collection agencies under Dodd-Frank Title X. For state-specific deceptive trade practices, State Attorneys General enforce state UDAP statutes.
What is the fastest method to recover money lost to a fraudulent merchant?
The fastest remedy is filing a formal billing dispute with your card issuer under the Fair Credit Billing Act (FCBA for credit cards) or Electronic Fund Transfer Act (EFTA for debit cards). Banks are required to acknowledge disputes within 30 days and provide provisional credit while conducting an inquiry.
Can the Better Business Bureau (BBB) force a company to issue a refund?
No. The BBB is a private non-profit organization with zero governmental, regulatory, or subpoena power. While BBB mediation can occasionally prompt voluntary customer service resolutions, official legal complaints must always be filed with your State Attorney General and the FTC.
HowToReport.org is an independent educational site — not a government agency. We link to official .gov and .org sources, but we cannot file a complaint for you or give legal advice. Read our full Legal Disclaimer & Safe Harbor →
Damages Under ,000? Check Your State Small Claims Limit
If administrative complaints fail to recover your financial losses, you can sue in local small claims court without expensive attorney fees. Select your state below for instant dollar limits and statutory deadlines:
Related Statutory Reporting Guides & Citizen Protections
Official step-by-step reporting protocols in this regulatory category.

What happens next
- Most agencies send an acknowledgment or reference number — save it with your copies.
- Investigations vary by agency; complex cases can take weeks or months.
- If you do not hear back within the timeframe listed on the agency site, follow up in writing.
- Keep reporting to additional agencies if your issue crosses categories (for example, fraud plus billing).
1 thought on “How to Report Consumer Fraud: The Complete Master Guide”