
⚡ Quick Answer: How to Report a Debt Collector
- Immediate Cease-and-Desist: Mail a formal Cease-and-Desist Notice via USPS Certified Mail; under 15 U.S.C. § 1692c(c), third-party debt collection agencies are legally prohibited from contacting you after receiving written notice.
- Statutory Debt Validation: Demand full debt verification under 15 U.S.C. § 1692g within 30 days of initial contact; collectors must freeze collection efforts until providing signed promissory notes and original creditor accounting.
- Financial Statutory Damages: Report abusive harassment to the CFPB and FTC; statutory damages of up to $1,000 per FDCPA violation plus reasonable attorney’s fees can be recovered directly in court without proving actual monetary injury.
⚖️ Facing Damages or Unreturned Funds Under $25,000?
Check your state small claims court dollar ceiling, statutes of limitations, and attorney representation rules.
How Do I Report a Debt Collector and Stop Abusive Harassment?
When dealing with debt collectors, aggressive communication tactics and deceptive threats often cross into unlawful territory. If an agency violates federal law, consumers have enforceable statutory mechanisms to file a formal complaint against a debt collector with a primary federal agency and compel the debt collector to stop all unapproved communication.
Understanding what collectors can and cannot do is essential for resolving chronic debt collection issues:
- When Collectors May Contact You: Debt collectors may only communicate between 8:00 AM and 9:00 PM local time. If a debt collector contacts you after hours or calls your workplace after being informed your employer prohibits personal calls, they violate 15 U.S.C. § 1692c.
- Prohibited Deceptive Tactics: A debt collector cannot threaten arrest, simulate legal process, falsely claim to be an attorney, or misrepresent the legal status or amount of the debt under 15 U.S.C. § 1692e.
- Right to Dispute and Freeze Collection: Once you timely dispute the debt in writing within 30 days of the validation notice, the agency must immediately cease all efforts to collect the debt until written verification is obtained and mailed to you.
- Credit Reporting Protections: Collectors cannot report false or unverified account balances to credit reporting bureaus. If an account is disputed, the collector must flag the trade line as disputed under both the FDCPA and the Fair Credit Reporting Act (FCRA).
You can report an abusive debt collector directly to the Consumer Financial Protection Bureau (CFPB) and the Federal Trade Commission (FTC). The Fair Debt Collection Practices Act (FDCPA) prohibits harassment, false statements, and unfair practices. Submit complaints online to trigger investigations into illegal debt collection tactics.
- Gather Evidence: Save voicemails, record call times, and keep copies of all written correspondence and collection letters.
- File Your Report: Submit a formal complaint through the CFPB website and the FTC’s online reporting portal.
- Follow Up: Send a certified “cease and desist” letter to the agency, or consult a consumer rights lawyer.
Falling behind on bills is incredibly stressful, but owing a debt does not strip you of your legal rights. The debt collection industry is heavily regulated by the federal Fair Debt Collection Practices Act (FDCPA), which strictly limits how, when, and where a third-party collection agency can communicate with you.
Unfortunately, many aggressive collection agencies—and outright “phantom debt” scammers—routinely ignore these laws, utilizing intimidation, repeated late-night phone calls, and threats of imprisonment to extort payments. If a debt collector crosses the line from attempting to collect a debt to engaging in harassment and abuse, you must document their actions and escalate the issue to federal regulators and civil courts.
Legitimate debt collectors cannot issue arrest warrants, suspend your driver’s license, or send police to your home. If a caller claims to be a “process server” or law enforcement official and demands immediate payment via a prepaid gift card or wire transfer to avoid arrest, hang up immediately. This is a criminal extortion scam, not a real debt collector.
Understanding the FDCPA: Warning Signs & Illegal Tactics
The FDCPA applies exclusively to third-party debt collectors (agencies hired to collect debts on behalf of another company) and debt buyers. It generally does not apply to the original creditor (e.g., the local hospital where you incurred the medical bill). Any violation of the FDCPA gives you the right to sue the collection agency.
The Debt Collector Red Flag Framework
1. Harassing Call Patterns
Calling repeatedly throughout the day, calling before 8:00 AM or after 9:00 PM (your local time), or using obscene/profane language.
2. Illegal Disclosures
Calling your employer, neighbors, or family members and explicitly telling them that you owe a debt. (They may only contact third parties once to locate you).
3. Workplace Contact
Continuing to call your place of employment after you have explicitly told them (verbally or in writing) that your employer prohibits such calls.
4. False Threats of Violence
Threatening physical violence, falsely claiming to be an attorney, or threatening to garnish your wages without first obtaining a valid court judgment.
Where to Report: Official Agencies & Jurisdiction Breakdown
If a debt collector breaks the law, you must report them to the federal agencies tasked with auditing financial institutions and protecting consumers. A high volume of complaints can result in the agency being permanently shut down.
Debt Collection Enforcement Matrix
Step-by-Step Guide to Filing Your Official Report
To successfully stop the harassment and penalize the debt collector, you must build a verifiable evidentiary file. Follow these steps sequentially.
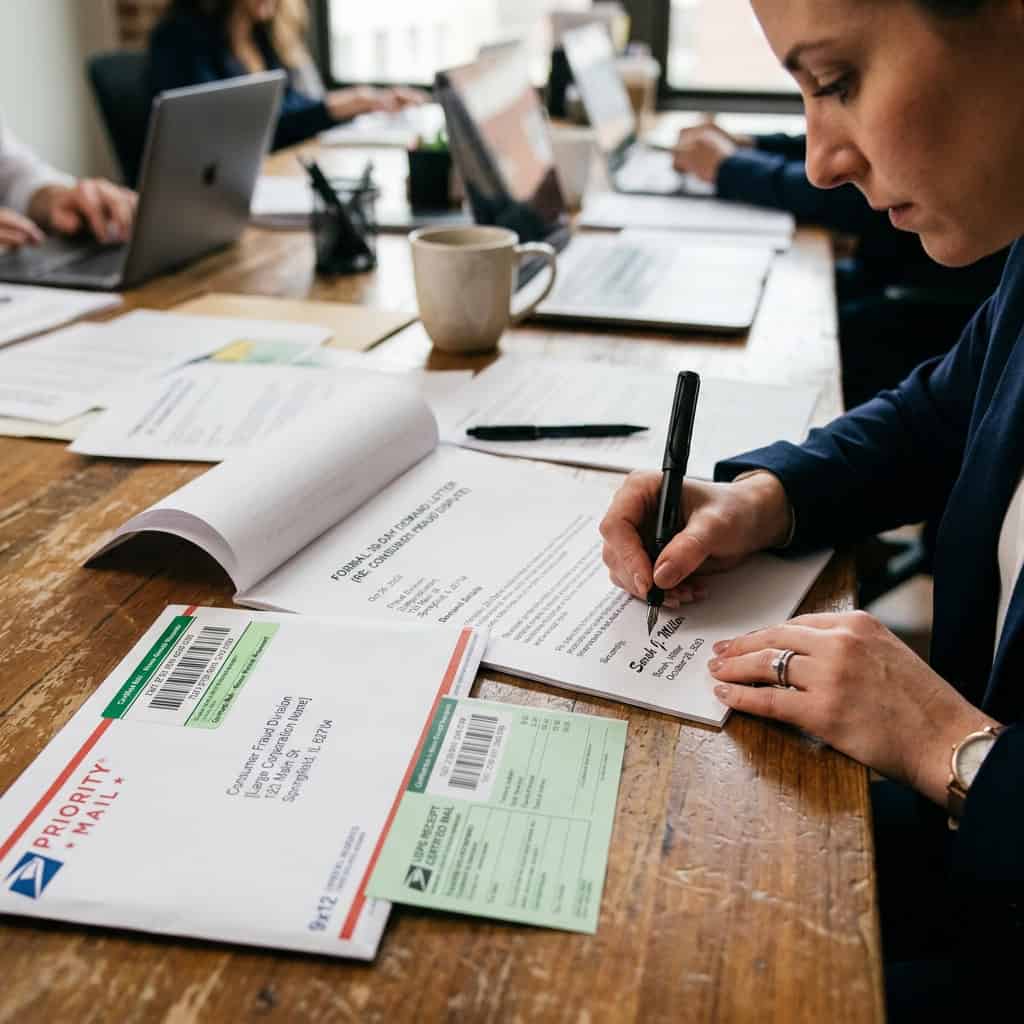
Step 1: Document the Harassment
Do not engage in screaming matches with the collector. Instead, become a meticulous record-keeper. Buy a notebook and log the exact date, time, and phone number of every call. Save all threatening voicemails to your computer. Keep copies of every letter they send you.
Step 2: Submit a Formal CFPB Complaint
Navigate to ConsumerFinance.gov/complaint. Select the “Debt Collection” category. Upload your call logs and any letters you received. The CFPB will route the complaint directly to the compliance department of the collection agency. In many cases, simply receiving a CFPB inquiry causes the agency to immediately drop the account and cease all contact.
⚖️ Your Statutory Rights When Facing Unfair Debt Collection Practices
Federal and state laws establish your absolute right to file a complaint when experiencing unfair debt collection practices. Under the FDCPA, collectors cannot call you before 8 a.m. or after 9 p.m., nor can they demand immediate payment for a debt you have already paid. If you can’t afford to pay or believe an agency is operating illegally, you can demand the collector to stop contacting you and report them directly to your state attorney general’s office and the CFPB. If violations continue, consumers have the legal right to file a lawsuit in federal court to recover actual and statutory damages.
Step 3: File with the FTC and State Regulators
File a parallel report at ReportFraud.ftc.gov to ensure the agency’s abusive tactics are logged in the federal Consumer Sentinel Network. Next, locate your state Attorney General’s Consumer Protection Division and file a complaint there, as many states have laws that are even stricter than the federal FDCPA.

Step 4: Send the FDCPA Cease and Desist Letter
You have the absolute legal right to demand a debt collector stop contacting you. You do not need a lawyer to do this. You simply must put it in writing. Once they receive a written “Cease and Desist” letter, the FDCPA dictates they can only contact you one final time to confirm they are stopping communication or to notify you of a specific legal action (like filing a lawsuit).
Evidence Preparation Checklist & Filing Timeline
Organize your defense and reporting strategy to ensure you retain maximum legal leverage.
4-Stage Debt Harassment Resolution Roadmap
Within 30 Days: Demand Validation
When contacted, immediately request a written “Validation of Debt” to force them to prove they legally own the account.
Send Cease & Desist
If harassment continues, mail the formal FDCPA Cease and Desist letter via USPS Certified Mail with a Return Receipt.
File Federal Complaints
Submit your call logs and evidence of FDCPA violations to the CFPB and the FTC.
Civil FDCPA Litigation
If they continue to call after receiving the Cease and Desist, retain an attorney to sue them for $1,000 in statutory damages.
To immediately halt all harassing communications, copy and paste this formal template. You must mail this via USPS Certified Mail with a Return Receipt so you have a judge-admissible signature proving they received it.
[Date]
VIA CERTIFIED MAIL RETURN RECEIPT REQUESTED (# [Tracking Number])
To: [Collection Agency Name]
Address: [Agency Street Address, City, State, ZIP]
RE: Account Number [Insert Account Number] / Cease and Desist Notification
Dear Sir or Madam,
I am writing to you in response to your recent communications regarding the above-referenced account.
Pursuant to my rights under the Fair Debt Collection Practices Act (FDCPA), 15 U.S.C. § 1692c(c), I am hereby formally demanding that you cease and desist all communication with me, as well as my family members, friends, and employer, regarding this debt.
This includes, but is not limited to, phone calls, letters, text messages, emails, and any other form of communication. I also explicitly notify you that my employer prohibits me from receiving debt collection calls at my place of employment.
Additionally, if you fail to comply with this formal demand and continue to contact me, I will immediately file formal complaints with the Consumer Financial Protection Bureau (CFPB) and my State Attorney General. I also reserve the right to retain an attorney and pursue civil litigation against your agency for statutory damages under the FDCPA.
Govern yourselves accordingly.
Sincerely,
[Your Printed Name]
[Your Signature]
[Your Contact Information]
Common Myths vs. Legal Realities About Debt Collection
Debt collectors rely heavily on intimidation and consumers’ ignorance of the law. Understand your ironclad statutory rights before answering the phone.
Myth vs. Fact
“If I don’t pay the medical bill or credit card, the debt collector will have me arrested for fraud.”
There are no “debtor’s prisons” in the United States for consumer debts like credit cards or hospital bills. It is a severe FDCPA violation for a collector to threaten arrest. (Note: This does not apply to unpaid taxes or child support).
“I can’t afford a lawyer to sue a debt collector, so there is nothing I can do.”
Because the FDCPA includes a “fee-shifting” provision, the collection agency must pay your attorney’s fees if you win. Therefore, consumer protection attorneys routinely take strong FDCPA harassment cases with zero upfront cost to you.
Frequently Asked Questions: Debt Harassment Protections
What can I do if I’m being harassed by a debt collector?
If you face debt collector harassment: (1) Keep a detailed communication log noting date, time, and agent identity, (2) Send a certified FDCPA Cease and Desist letter demanding the collector to stop phone calls, (3) Request full debt validation within 30 days, (4) File an official complaint against the debt collector with the CFPB (consumerfinance.gov/complaint), and (5) Consult a consumer protection attorney to claim up to $1,000 in statutory damages under 15 U.S.C. § 1692k.
What is the 11-word phrase to stop debt collectors?
The standard phrase used by consumer advocates is: “Please cease and desist all communication with me regarding this alleged debt.” Under Section 805(c) of the Fair Debt Collection Practices Act (15 U.S.C. § 1692c(c)), once a collector receives written notice to cease communication, the collector cannot contact you again except to advise that collection efforts are terminated or that a specific legal remedy (such as a civil lawsuit) will be invoked.
Do I legally have to pay back debt collectors?
You only have a legal obligation to pay if the debt collector can legally prove ownership of a valid, enforceable debt and the statute of limitations has not expired. Debt buyers frequently purchase bundled delinquent accounts with missing documentation. If the collector fails to provide verified chain-of-title or if the state statute of limitations has elapsed, the debt becomes “time-barred,” meaning the collector cannot sue you or threaten legal action to collect the debt.
What is the worst a debt collector can do?
A debt collector cannot have you arrested, send law enforcement to your home, or seize your assets without a court judgment. The worst a legitimate collector can legally do is report negative payment history to consumer credit reporting agencies or file a civil lawsuit in state court. Even if they secure a judgment, statutory exemptions protect essential income, Social Security benefits, disability payments, and primary residences from garnishment.
What is the “Statute of Limitations” on a debt?
The statute of limitations is the legally mandated time frame (usually 3 to 6 years, depending on your state and the type of contract) during which a creditor can successfully sue you for a debt. Once the statute of limitations expires, the debt becomes “time-barred.” While a collector can still legally ask you to pay a time-barred debt, they cannot sue you or threaten to sue you. Warning: making a partial payment can “restart” the clock in some states.
Can a debt collector contact me on social media?
Under new CFPB rules, debt collectors can technically message you on social media, but their messages must be strictly private (not posted on your public timeline), they must identify themselves as a debt collector, and they must provide a simple, easily accessible way to opt out of further digital messages.
What should I do if a collector serves me with a lawsuit?
Do not ignore a court summons. If you fail to respond to the lawsuit or fail to appear in court, the judge will issue a “default judgment” against you. This grants the collection agency the legal power to freeze your bank accounts or garnish your wages. Immediately consult a local consumer attorney or legal aid society to file an answer with the court.
How do I dispute a debt I don’t owe?
If you believe the debt is fraudulent (e.g., identity theft) or the amount is incorrect, send a written “Debt Validation Letter” within 30 days of their initial contact. By law, they must cease collection efforts until they mail you documentation proving you actually owe the money.
- Consumer Financial Protection Bureau (CFPB): Submit official debt collection complaints and violations directly to the federal portal. — ConsumerFinance.gov
- Fair Debt Collection Practices Act (FDCPA): The primary federal statute (15 U.S.C. 1692) governing third-party debt collection conduct.
- National Association of Consumer Advocates (NACA): Directory of specialized attorneys who sue debt collectors for FDCPA violations. — ConsumerAdvocates.org
HowToReport.org is an independent educational site — not a government agency. We link to official .gov and .org sources, but we cannot file a complaint for you or give legal advice. Read our full Legal Disclaimer & Safe Harbor →
Damages Under ,000? Check Your State Small Claims Limit
If administrative complaints fail to recover your financial losses, you can sue in local small claims court without expensive attorney fees. Select your state below for instant dollar limits and statutory deadlines:
Related Statutory Reporting Guides & Citizen Protections
Official step-by-step reporting protocols in this regulatory category.
Official sources
Use these official channels for your complaint — verify details on the agency site before you submit.
- Consumer Financial Protection Bureau (CFPB) — 1-855-411-2372 (Online 24/7 | Phone Mon-Fri 8am-8pm ET)
- Official reporting portal
What happens next
- Most agencies send an acknowledgment or reference number — save it with your copies.
- Investigations vary by agency; complex cases can take weeks or months.
- If you do not hear back within the timeframe listed on the agency site, follow up in writing.
- Keep reporting to additional agencies if your issue crosses categories (for example, fraud plus billing).